Which one is right for you: a second apartment, or a managed farm plot
The right answer depends less on which asset is better and more on which of two things you are buying: an asset you can borrow against and sell quickly, or land held in your own name that is worked for you and used by your family.
If you have had a good year and do not want the money sitting idle in another flat or in the market, you are weighing the two choices a Bengaluru professional most often compares. A second apartment suits a buyer who wants to finance most of the price with a home loan, earn rent from day one, and sell into a deep resale market. A managed farm plot suits a buyer who wants a freehold title in his own name, an operator to do the farming, and somewhere the family goes, and who is not relying on a loan or a quick exit.
Neither is the better investment in the abstract, and this page will not tell you one is. It compares the two on the dimensions that decide the choice, names where each honestly wins, and puts no return, rental yield or appreciation number on either, because none of those can be projected on a page that does not know your project, your market or your own position.
Managed farmland versus a second apartment, dimension by dimension
This table sets a second apartment and a managed farm plot side by side across the dimensions that decide the choice: entry cost, financing, liquidity and exit, effort, use value, running cost, and risk.
Dimension
A second apartment
A managed farm plotEntry cost | Priced per square foot of built-up area, in a city micro-market. Project-specific; no figure published here. | Priced per square foot of land, usually over a larger area further from the city. Project-specific; no figure published here.
Financing | A home loan, at 75 to 90 percent of value under RBI norms, at prevailing floating rates. | Generally bought with your own funds. A standard home loan does not finance agricultural land, and agri-loan routes carry farmer-eligibility conditions.
Liquidity and exit | A deep, familiar resale market with many buyers and property portals. | A thinner resale market, a narrower pool of eligible buyers, and resale help that depends on the operator.
Effort | Find tenants, manage vacancies and repairs, or pay an agent to do it. | The operator runs the planting, upkeep, harvest and sale. You do none of the farming.
Use value | Usually a second flat you let to a tenant, not one you use yourself. | With a cottage, a place the family visits, with produce from a worked estate.
Running cost | Monthly society charges, property tax, and repair and tenant costs. | An annual management fee, charged per square foot of plot area, covering common-area and plantation upkeep.
Risk | A depreciating building, tenant and vacancy risk, and possession risk on an under-construction flat. | Title and land-record risk, illiquidity, dependence on the operator, and agricultural-land rules such as DC conversion.
No return, rental yield or appreciation figure is attached to either option here. Both are project-specific and belong in the agreement and in a conversation with your chartered accountant. Several of these factors are genuine wins for the apartment, and they are worth stating plainly first.
Where a second apartment is the better choice
A second apartment is the better choice in four situations, and a comparison that will not say so is not worth reading.
The first is when you need to borrow most of the price. An apartment is financeable with a home loan at 75 to 90 percent loan-to-value under RBI norms, while a managed farm plot on agricultural land generally is not, so the apartment lets you buy with a smaller down payment (NoBroker, 13 February 2026).
The second is when you need income from the asset now. A flat can be let for rent from the month it is ready. A farm plot produces income on a farming timeline, not from day one, so if you are counting on cash flow soon, the apartment is the fitter tool.
The third is when you may need to sell within a few years. An apartment sells into a broader, more familiar resale market than farmland, with more buyers and established channels (Mangofolks; NoBroker, 13 February 2026). If liquidity matters to you, that is a real edge.
The fourth is when you would rather not learn a new kind of asset. An apartment is familiar, with a known process. A managed farm plot brings land records, agricultural rules and an operator relationship to understand, and for a buyer short on time that is a cost of its own.
These are real advantages, and for many buyers they settle it. Where a managed farm plot pulls ahead is on a different set of factors, ones a loan and a resale market do not capture.
Where a managed farm plot is the better choice
A managed farm plot is the better choice when you want land held freehold in your own name, worked for you, and used by the family, and you are not depending on a loan or a quick sale.
Start with the title. A managed farm plot is held freehold, with the title registered directly in the buyer's name. A second apartment is a unit in a building with an undivided share of the land beneath it. If owning the ground itself matters to you, those are different kinds of possession.
Then the work. With a managed plot, the operator finds legally sound land, farms it, and markets the harvest, and hands the owner an annual yield statement. A rented apartment still needs a landlord who chases tenants and repairs. This is the case for the buyer whose sentence is “I want land, but I do not want to deal with it.”
There is also a difference in what wears out. An apartment bundles a depreciating building with the land under it. Buildings age and need repair; land does not deteriorate. That is a structural point about the two assets, not a claim that one will appreciate faster than the other.
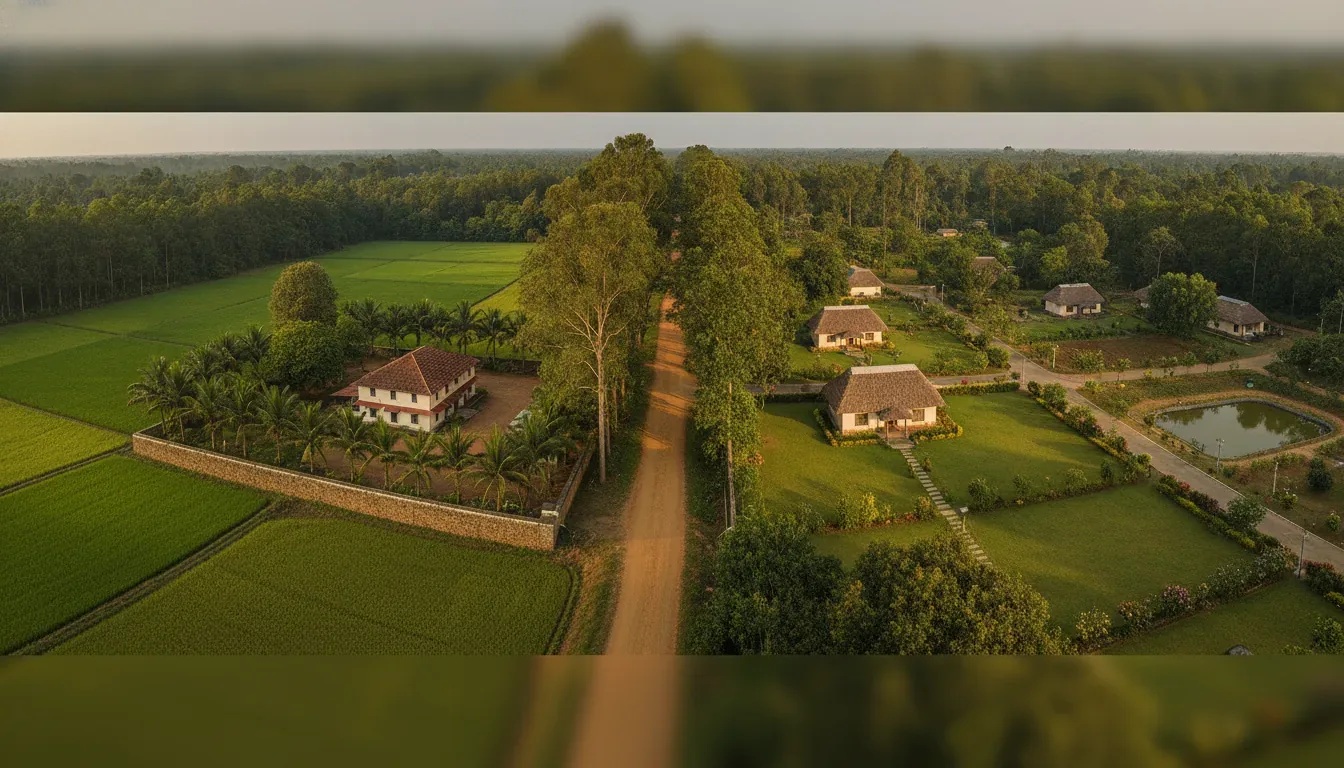
Finally, use. A managed farm plot can carry a cottage the family visits, in the Bengaluru corridors or the Western Ghats, with produce from an estate that is worked. A second apartment is usually a place a tenant lives, not the owner.
One caution belongs here, because a managed plot is only as good as the operator still running it years later. Ask how long the operator has been going, how many projects it has finished, and whether owners are still on estates it sold a decade ago. Vibez Estates, for example, has been operating since 2009, seventeen years, with 25+ projects delivered and 1,100 acres under management as at. The single factor that most changes this whole decision, though, is not the operator. It is financing.
The financing difference, and why it changes the whole decision
The single biggest practical difference between the two is financing: a home loan finances an apartment, while a managed farm plot on agricultural land generally does not qualify for one.
A residential apartment is financeable with a home loan. Under RBI norms, banks lend up to 90 percent of value on smaller tickets, up to 80 percent in the middle band and up to 75 percent above the top band, at prevailing floating rates, repaid over up to twenty to thirty years . A neutral portal puts the working range at 75 to 85 percent of apartment cost.
A managed farm plot sits on agricultural land, and a standard home loan does not finance that. Agricultural-land purchase is funded through separate routes, an agriculture term loan, a Kisan Credit Card, or a loan against property, which typically cover 70 to 80 percent of land value and skew toward farmer eligibility, marginal and small farmers and tenant farmers (Tata Capital, updated 21 August 2026). A salaried or self-employed Bengaluru buyer usually does not meet those conditions, so a managed farm plot is generally bought with own funds. That gap changes the decision, not just the paperwork. A home loan lets you control a larger asset with less of your own capital and let the rent cover part of the EMI. A managed farm plot ties up more of your own money at the outset, which is why it suits a buyer who already has capital sitting idle rather than one who needs to borrow. Rates and loan-to-value rules change, so confirm the current terms with your bank and your chartered accountant before you decide. How you finance each option also shapes how you sell it.
Exit: who actually buys each one back from you
An exit differs sharply between the two: an apartment sells into a deep resale market, and a managed farm plot into a thinner one with a narrower pool of eligible buyers.
An apartment sells into an established resale market, with a broad buyer base, agents and property portals. That is what makes it the more liquid of the two.
A managed farm plot sells into a thinner market. Agricultural land carries eligibility rules on who may buy it, and an NRI is barred under FEMA from buying agricultural land in India at all, so the pool of buyers is smaller from the start. That does not make it unsellable, but it does make it slower, and a buyer should price that in.
Two questions settle the rest. Ask whether the operator helps you find a buyer, and ask whether the plot and its maintenance agreement transfer cleanly to the new owner. Be plain with yourself about the answer: the managed-farmland resale market is thinner than an apartment's, and the honest position today is. Until an operator can show you what resale help exists, treat the resale route as real but limited, and get the transfer terms in writing before you buy. Tax at exit is its own question: capital-gains treatment on agricultural land differs from that on a residential flat and turns on the land's classification and location, so it belongs with your own CA
Use value: the dimension most buyers underweight
Use value is what the asset gives you while you hold it, beyond any resale number, and it is the factor a return calculation leaves out.
For a second apartment, use value to the owner is usually low, because a second flat is typically let to a tenant. Its value to you is the rent, not the use.
For a managed farm plot with a cottage, use value is the point. It is a place the family goes, with produce from a worked estate, and that is worth something a spreadsheet does not record.
There is an honest limit, and it is the apartment's fair rejoinder here. Use value is only real if you will make the trip. An estate several hours away that the family visits once is a cost, not a use. If you know the visits will not happen, discount this factor to zero and let the financial ones decide, which is the sensible way to make the whole call.
How to choose honestly between the two
The honest way to choose turns on your own situation, not on a verdict someone hands you.
Four questions do most of the work. Do you need to borrow to buy it? Do you need income or an exit within a few years? Will your family use it? And are you buying an asset to hold, or a place to use? Yes to the first two points you toward the apartment. Yes to the last two points you toward the managed farm plot.
Then take four questions to your own chartered accountant: the annual outgo on each, the financing you qualify for, the tax treatment of the income and of the exit, and whether the allocation fits the rest of your portfolio.
The bottom line is narrow on purpose. This page can tell you which option suits which situation. It cannot tell you which will make more money, because no honest page can put a return on either without knowing the project, the market and your own position. That number is a conversation for the agreement and for your CA, not a promise from a comparison.